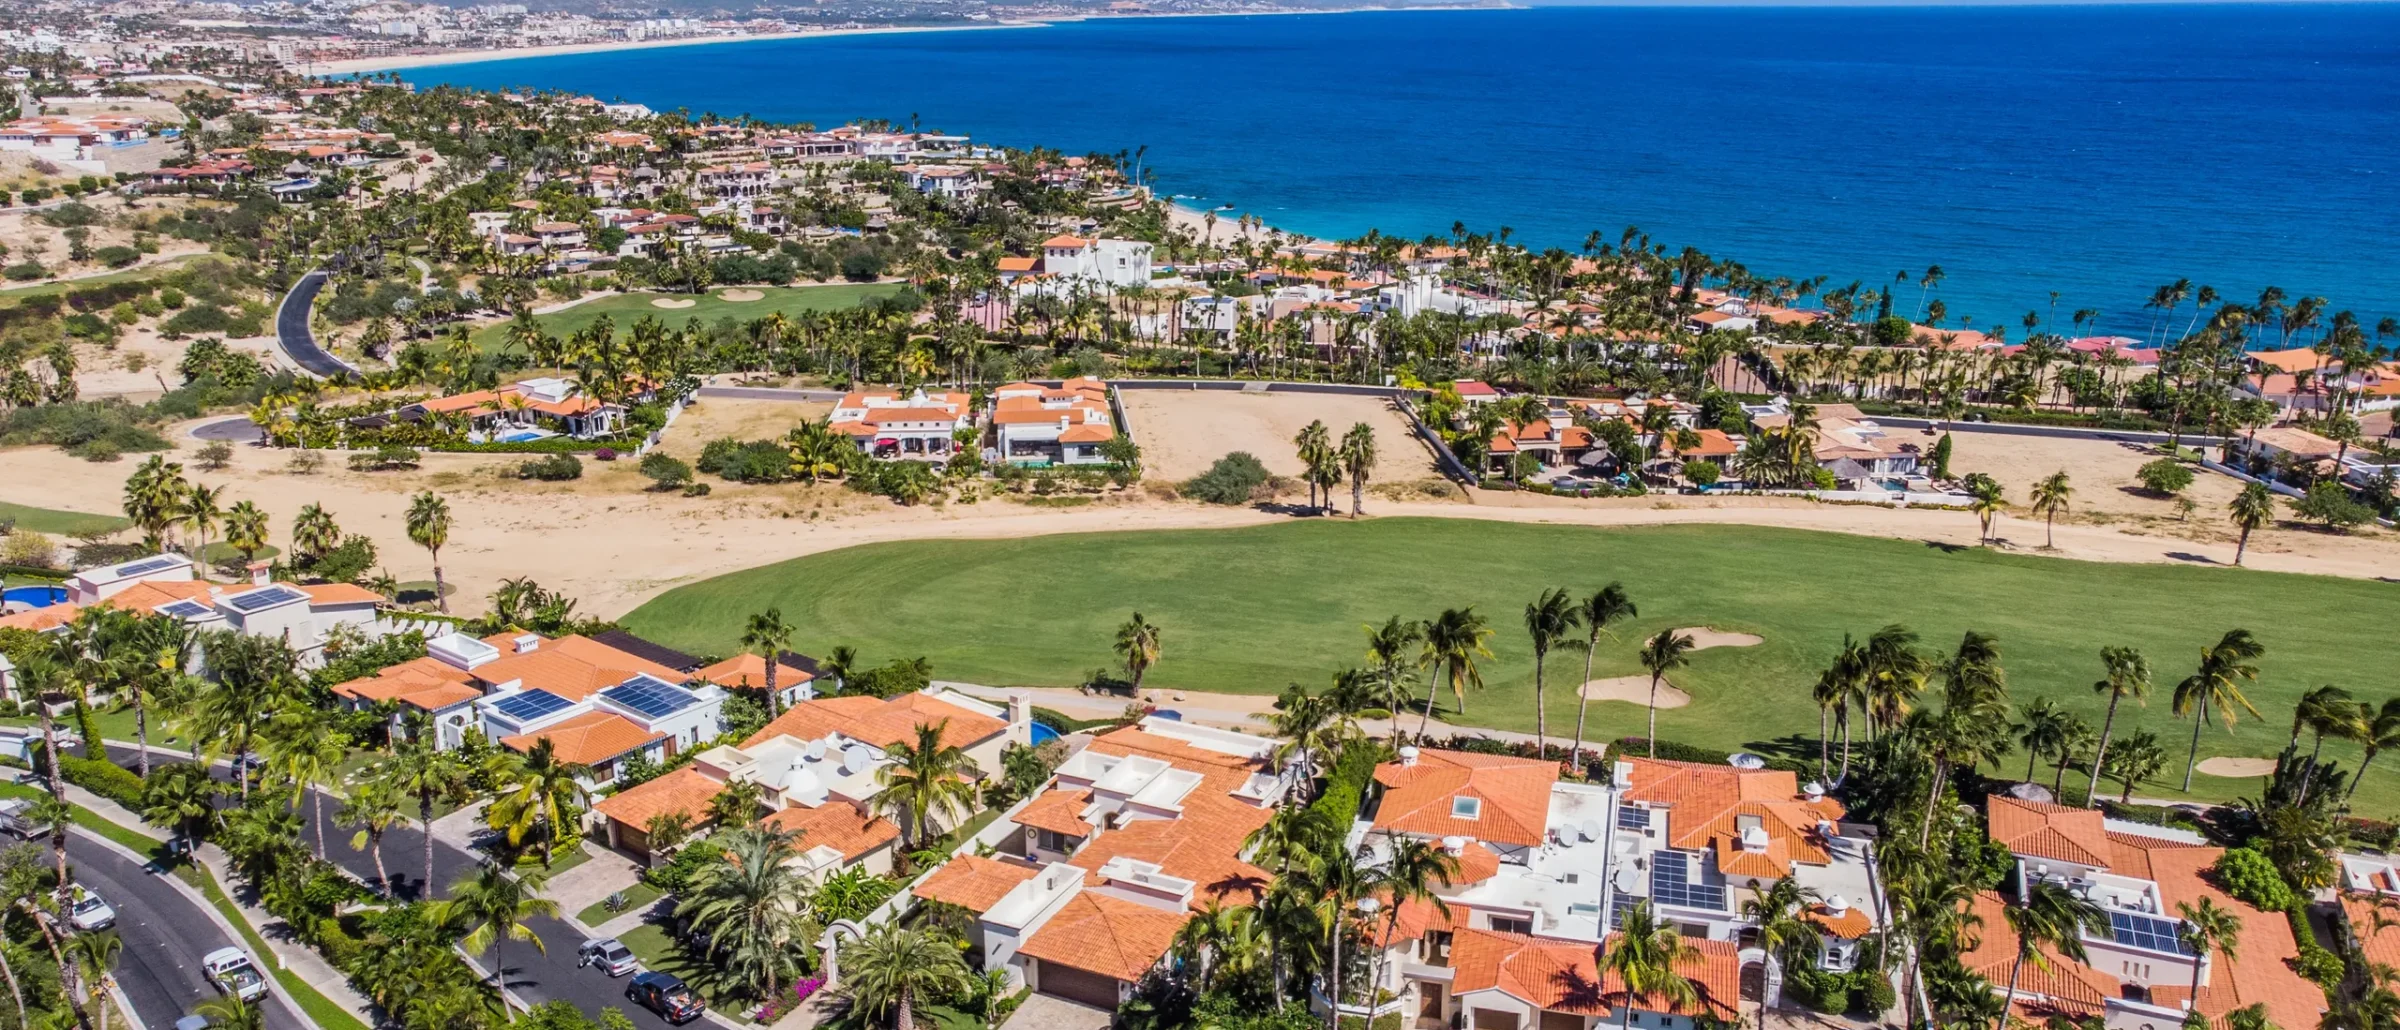
When foreign investors, retirees, and second-home purchasers explore residential real estate in Baja California Sur, the legal mechanism of property ownership is often their first point of inquiry. Misconceptions persist that foreigners cannot legally own land along Mexican coastlines, or that acquiring property requires complex corporate maneuvering.
Mexican federal law provides clear, constitutionally protected mechanisms for foreign buyers to acquire, hold, develop, lease, and transfer coastal residential real estate. Non-Mexican citizens acquire luxury villas, custom homesites, and condominiums in destinations like Pedregal and Palmilla with full title security.
The two legal structures available to foreign purchasers are the residential bank trust (fideicomiso) and the Mexican commercial corporation. Selecting the appropriate structure depends on whether the property is intended as a private residence or an active commercial enterprise.
This guide analyzes the statutory framework governing coastal ownership, compares the fideicomiso bank trust against commercial corporate structures, and reviews key United States tax classifications under official IRS guidance.
The Constitutional Framework and the Mexican Restricted Zone
Understanding property ownership in Los Cabos requires examining Article 27 Section I of the Mexican Federal Constitution (Constitución Política de los Estados Unidos Mexicanos).
What Defines the Restricted Zone?
Article 27 Section I of the Mexican Constitution establishes that the nation originally owns all lands and waters in Mexico, retaining the right to transmit title to private individuals to create private property. The constitution permits Mexican citizens and Mexican companies to acquire ownership of lands and waters, and allows the Mexican State to grant similar rights to foreign nationals under the condition that they agree before the Ministry of Foreign Affairs (Secretaría de Relaciones Exteriores / SRE) to consider themselves Mexican nationals regarding such property (the Calvo Clause) and not invoke the protection of their home governments.
Within a specific territorial boundary, the Mexican Constitution establishes a strict prohibition on direct fee-simple land title by non-citizens:
- Land located within 100 kilometers of international land borders.
- Land located within 50 kilometers of Mexican coastlines.
Because the entire Baja California peninsula is surrounded by the Pacific Ocean and the Sea of Cortez, every property in Los Cabos, from San José del Cabo to Cabo San Lucas and the East Cape, is situated inside the constitutional Restricted Zone.
The official text of IRS Revenue Ruling 2013-14 summarizes this constitutional provision:
"The Mexican Federal Constitution prohibits non-Mexican persons from directly holding title to residential real property in certain areas of Mexico (‘restricted zones’). Non-Mexican persons, however, may hold residential real property located in the restricted zones through an MLT with a Mexican bank after obtaining a permit from the Mexican Ministry of Foreign Affairs."
The Equitable Nature of Fideicomiso Property Rights
Holding property through a fideicomiso does not diminish the buyer’s authority over the asset. The fideicomiso structure provides the foreign beneficiary with equitable beneficial ownership rights equivalent to fee-simple ownership in common-law jurisdictions.
Under Article 12 of the Ley de Inversión Extranjera (Foreign Investment Law), the rights of use and enjoyment (utilización y aprovechamiento) granted under a fideicomiso include the right to use and enjoy the property, as well as the right to obtain fruits, products, and any yields resulting from its operation and lucrative exploitation.
As the primary trust beneficiary, the foreign owner possesses the exclusive legal right to:
- Occupy and enjoy the residence as a private home.
- Remodel, renovate, or construct architectural improvements on the parcel.
- Lease the property to tenants and collect rental revenues directly.
- Secure financing or encumber trust rights with a registered mortgage credit.
- Sell the property on the open market and retain all capital proceeds.
- Designate primary and substitute beneficiaries in the public deed to transfer property to heirs.
What Is a Fideicomiso? The Mexican Bank Trust Explained
A fideicomiso is a tripartite contractual legal trust established under Mexican federal legislation and executed before a state-commissioned Notario Público. Unlike a standard common-law discretionary trust where a trustee often exercises broad managerial authority, a Mexican real estate fideicomiso functions as a passive title-holding mechanism.
The Three Parties to the Trust
Every real estate fideicomiso involves three distinct participants:
- The Trustor (Fideicomitente): The seller or current property owner who transfers the title of the real estate into the trust structure at closing.
- The Trustee (Fiduciario): An authorized Mexican commercial banking institution licensed by federal banking authorities (such as BBVA México, Banco Banorte, Scotiabank Inverlat, or Banco Intercam) to operate a specialized fiduciary department. The trustee bank holds bare legal title strictly for the benefit of the designated buyer.
- The Beneficiary (Fideicomisario): The foreign buyer who holds equitable title, complete control, occupancy rights, and full authority to direct the trustee regarding future conveyances or encumbrances.
50-Year Duration and Integrated Succession
Under Article 13 of the Foreign Investment Law, residential fideicomisos are established for a statutory duration of up to 50 years. Under Article 12 of the Foreign Investment Regulations (Reglamento de la Ley de Inversión Extranjera / RLIE), the trust beneficiary or trustee may apply for successive 50-year extensions within 90 business days prior to trust expiration. This renewal mechanism ensures that foreign owners and their families can hold property across multiple generations without interruption.
A major structural advantage of the fideicomiso is its integrated estate planning capability. When drafting the public deed (escritura pública), the buyer designates primary and substitute beneficiaries directly within the document.
If a primary beneficiary passes away:
- Beneficial rights transfer directly to the designated substitute beneficiaries upon presentation of an official death certificate and standard identification to the trustee bank.
- The transfer occurs without requiring Mexican probate court proceedings.
- The transfer avoids the time, expense, and complexity of international cross-border probate.
Setup and Administration Procedures
Establishing a residential fideicomiso requires two administrative steps coordinated by your Notario Público and closing team:
- Foreign Affairs Permit: Obtaining a formal acquisition permit from the Ministry of Foreign Affairs (SRE) under Article 11 of the Foreign Investment Law. Under Article 14 of the statute, the central SRE office resolves permits within five business days, and state delegations resolve applications within 30 business days, subject to administrative approval upon expiration (afirmativa ficta).
- Trustee Origination and Administration: Paying an initial trust setup fee to the designated Mexican trustee bank at closing, followed by an annual fiduciary administration fee billed by the bank for holding bare title.
For detailed information on how trust setup costs integrate into your overall transaction budget, consult our breakdown of buyer closing costs in Los Cabos.
Owning Real Estate Through a Mexican Corporation
While the fideicomiso is the standard vehicle for residential vacation homes and personal residences, foreign investors can also acquire real estate through a wholly owned Mexican corporation (Sociedad Anónima de Capital Variable / S.A. de C.V. or Sociedad de Responsabilidad Limitada / S. de R.L.).
Corporate Formation Mechanics
Under Mexican foreign investment regulations, foreign nationals are permitted to hold 100 percent of the shares or equity quotas in a Mexican commercial corporation.
Because a Mexican corporation is legally a domestic legal entity, it is permitted under Article 10 Fracción I of the Foreign Investment Law to hold direct, fee-simple title to real estate in the restricted zone without establishing a fideicomiso, provided the property is utilized for non-residential commercial activities.
Appropriate Commercial Use Cases
Acquiring property through a Mexican corporation is advantageous under specific business scenarios:
- Commercial Enterprises: Purchasing retail shopping plazas, office buildings, restaurants, or boutique hotels.
- Land Subdivision and Development: Acquiring acreage for residential subdivision, infrastructure installation, and parcel re-sale.
- Active Hospitality Portfolios: Operating an active commercial hotel or real estate business where corporate revenues and operating expenses are managed centrally.
Statutory Prohibition on Holding Personal Residences in Corporations
Foreign purchasers must not form a Mexican corporation solely to acquire a private, non-income-generating single-family residence in the Restricted Zone.
Under Article 10 Fracción II of the Foreign Investment Law, Mexican companies with foreign investment clauses are explicitly prohibited from acquiring direct fee-simple ownership of residential real estate within the restricted zone. When acquiring residential real estate in the coastal zone, corporations must acquire rights through a fideicomiso trust.
Attempting to hold a private personal residence in a corporation without genuine commercial activity creates regulatory non-compliance, forfeits individual primary residence capital gains tax exemptions upon resale, and introduces substantial monthly accounting expenses.
Operating a Mexican corporation introduces ongoing obligations:
- Monthly Fiscal Filings: Mexican commercial entities must submit monthly tax declarations to the federal tax authority (Servicio de Administración Tributaria / SAT), regardless of whether active income was generated during that monthly period.
- Mandatory Certified Accounting: Corporations must retain a licensed Mexican public accountant (Contador Público) to maintain official electronic ledgers and issue compliant electronic tax invoices (CFDI).
- Corporate Governance: The corporation must maintain official shareholder registers, hold annual general meetings, and protocolize major corporate actions before a Notario Público.
Side-by-Side Comparison: Fideicomiso vs. Mexican Corporation
To evaluate which ownership vehicle matches your acquisition goals, review the operational distinctions in the comparison table below:
| Feature / Consideration | Fideicomiso (Bank Trust) | Mexican Corporation (S.A. de C.V. / S. de R.L.) |
|---|---|---|
| Primary Use Case | Personal residences, vacation villas, condominiums, and passive rental homes | Commercial buildings, active hospitality businesses, multi-unit developments |
| Direct Land Title | Bank holds bare legal title; foreigner holds equitable beneficial interest | Corporation holds direct title for non-residential commercial activities |
| SRE Permit Required | Yes, required for coastal restricted zone residential trusts | Yes, corporate name authorization and foreign investment registration |
| Ongoing Maintenance | Annual trustee administration fee paid directly to the bank | Monthly accounting retainer, corporate record books, and SAT filings |
| Tax Filing Frequency | Annual income tax filing if generating rental income | Mandatory monthly SAT tax declarations plus annual corporate return |
| Estate Succession | Built-in beneficiary designations bypass probate courts | Share transfer governed by corporate bylaws, wills, or probate |
| Residential Capital Gains Exemption | Available for eligible individual owners subject to statutory rules | Not available to commercial business entities |
The Role of the Notario Público in Real Estate Transactions
Real estate conveyances in Mexico do not rely on standard private contracts alone. Every legal transfer of real property must be formalized and protocolized by a licensed Mexican Notario Público.
Under Articles 1 and 4 of the Ley del Notariado para el Estado de Baja California Sur (Decreto 93), the practice of the notariat is a public order function delegated by the State Executive to legal professionals holding official patents. A Mexican Notario Público acts as an impartial public officer responsible for the integrity and legality of the transaction.
The Notario’s statutory responsibilities include:
- Title Examination: Verifying the chain of title in the Public Registry of Property (Registro Público de la Propiedad) to confirm clear ownership and uncover any liens, mortgages, or encumbrances.
- Tax Withholding and Calculation: Calculating and collecting municipal acquisition taxes and state duties from the transaction parties under legal responsibility.
- Regulatory Verification: Confirming property tax (predial) certificates, municipal water clearances, and cadastral property boundaries.
- Public Deed Protocolization: Drafting the formal public deed (escritura pública), administering official signatures, and recording the deed in the public registry.
US and Cross-Border Tax Considerations: IRS Revenue Ruling 2013-14
For American purchasers, acquiring real estate in Mexico through a fideicomiso raises important tax classification questions under United States federal tax law.
IRS Revenue Ruling 2013-14: Land Trust Classification
In IRS Revenue Ruling 2013-14, published in Internal Revenue Bulletin 2013-26 (2013-26 I.R.B. 1267), the IRS addressed the federal income tax classification of Mexican land trusts established by US citizens to hold residential property in the Restricted Zone.
The ruling examined situations (such as Situation 1 and Situation 3) where a US purchaser obtained a permit from the Mexican Ministry of Foreign Affairs, executed a Mexican land trust agreement with an authorized Mexican bank, negotiated and paid the purchase price directly to the seller, and received legal title held by the bank subject to the agreement.
The IRS determined that because the trustee bank’s only duties under the agreement are to hold legal title to the property and transfer title at the direct instruction of the beneficiary:
- The Mexican land trust is not classified as a trust for US federal tax purposes under Treasury Regulation section 301.7701-4(a).
- The US beneficiary retains complete authority to manage, control, and lease the real estate, as well as the right to collect rental revenue.
- The US beneficiary bears the direct obligation to pay property taxes and liabilities associated with the home.
- The US purchaser is treated directly as the owner of the real property for US federal income tax purposes.
Under this official guidance, if the trustee bank holds title only to the residential property and engages in no broader active business operations, the arrangement is treated as a bare title-holding structure or disregarded entity, rather than an active fiduciary entity.
Professional Cross-Border Tax Counsel
Because individual tax situations depend on residency, personal estate structures, and rental operations, our team always advises foreign buyers to consult a certified public accountant specializing in cross-border US-Mexico tax compliance alongside their Mexican Notario Público.
Practical Steps for Acquiring Property in Los Cabos
If you are preparing to acquire a luxury property or homesite in Los Cabos, following a structured acquisition protocol ensures title security:
- Retain an Independent Notario Público Early: Select a licensed Notario Público to examine title records, municipal water certificates, and property tax status before transferring earnest money deposits.
- Choose an Established Trustee Bank: Select an institutional commercial bank with an active trust department in Baja California Sur.
- Designate Clear Succession Beneficiaries: Prepare full legal names, passport details, and relationship designations for your primary and substitute beneficiaries to be integrated directly into your public deed.
- Coordinate SRE Permit Filings Promptly: Ensure your closing agent submits trust permit applications to the Ministry of Foreign Affairs early in the escrow period to take advantage of statutory five-day to thirty-day processing windows.
Whether you are evaluating an oceanfront villa in Pedregal, a golf retreat in Palmilla, or a private estate in Puerto Los Cabos, working within Mexico’s established statutory frameworks guarantees complete security for your real estate investment.
Advisory Standard
Our multidisciplinary team provides objective market analysis, fiduciary guidance, and private transaction advisory across Los Cabos and Baja California Sur.